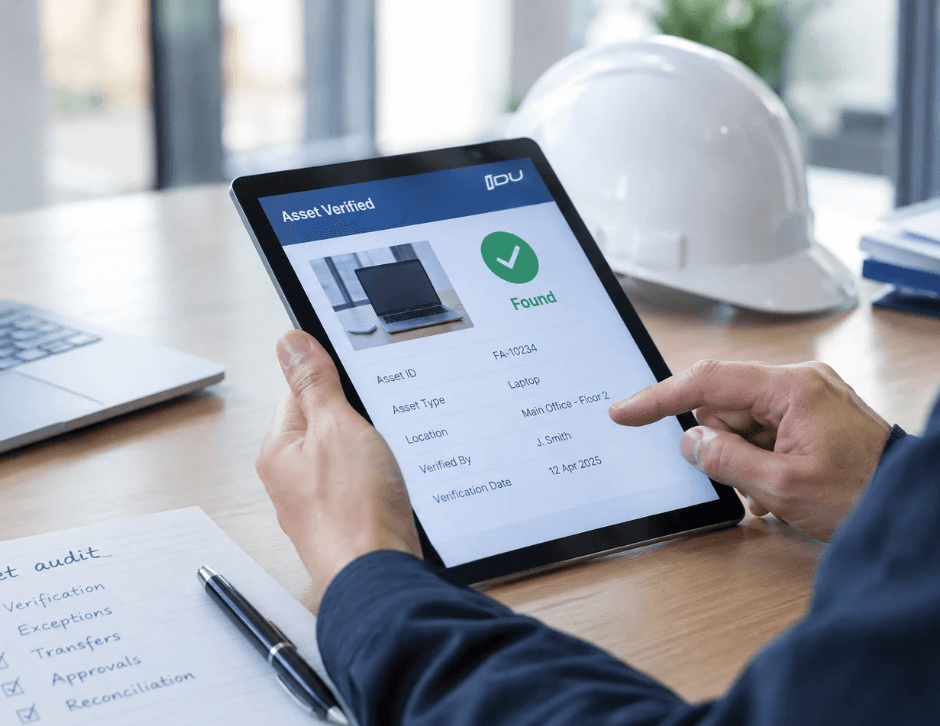
Fixed asset audit preparation should not begin when the audit request arrives. Yet Finance often has to gather schedules, search for fixed asset verification files, follow up on missing information and reconstruct transfers, disposals and approvals shortly before fieldwork.
The fixed asset register may contain the accounting record, but fixed asset audit readiness also requires reliable evidence that assets exist, are in the expected locations and have been subject to appropriate verification, review and approval.
The strongest approach is to generate fixed asset audit evidence through the normal asset-control process, rather than assemble it retrospectively.
What is fixed asset audit readiness?
Fixed asset audit readiness is the organisation's ability to provide reliable, current and traceable evidence about its assets when that evidence is required.
An audit-ready fixed asset process should enable an organisation to demonstrate:
- Which assets were included in the verification scope.
- When each asset was last verified and who performed the verification.
- Where the asset was found and whether an exception was identified.
- How movements, transfers and disposals were managed.
- Who reviewed and approved changes.
- How approved changes were aligned with the fixed asset register.
- Which assets and exceptions remain outstanding.
This is broader than having a completed asset list.
A spreadsheet may show that an asset was marked as found. Fixed asset audit readiness requires the organisation to demonstrate the process and evidence behind that conclusion.
How do you prepare fixed assets for an audit?
Good fixed asset audit preparation starts well before the auditors arrive.
Finance should be able to identify the assets within scope, establish when they were last verified, investigate exceptions, trace transfers and disposals, and retrieve the approval history for changes made to the register.
The evidence should already exist as part of the normal fixed asset verification and control process.
This reduces the need for Finance to reconstruct the history of an asset from spreadsheets, emails, photographs and paper sign-offs immediately before an audit.
Why does fixed asset audit preparation become difficult?
Asset information is often spread across several places.
The ERP contains the accounting record. Physical verification results may sit in spreadsheets, photographs in folders, and movement or disposal approvals in email.
Each item may exist, but the complete history is fragmented.
Finance must connect the asset record, physical verification, identified difference, supporting evidence, requested correction, approval and final register update.
As organisations grow, this becomes harder to manage consistently across multiple sites, departments, cost centres and managers.
Seven ways to improve fixed asset audit readiness
1. Define the fixed asset verification scope clearly
Audit readiness begins with clarity about the asset population being controlled.
Define the relevant entities, asset books, classes, locations, departments, cost centres, thresholds and verification periods. The scope should also address higher-risk assets and items that cannot be physically labelled.
A clearly defined population makes it possible to establish what should have been verified, what has been verified and what remains outstanding.
2. Record who verified each asset and when
A tick in a spreadsheet may show that someone marked an asset as found, but it may not reliably establish who completed the verification or when.
Each verification should identify the asset, authorised verifier, date, relevant location or cost centre, outcome and any exception or supporting information.
This distinguishes the financial record from the operational evidence and makes the age of that evidence visible.
3. Put responsibility close to the asset
Finance should govern the process, but may not be best placed to verify every physical item.
Operational managers are closer to the assets in their departments, branches or cost centres. They can verify assets within authorised areas, while Finance controls structures and reporting, and the asset register custodian reviews exceptions and approves appropriate changes.
Access can remain restricted to the locations, cost centres and asset classes relevant to each user.
This creates clearer accountability without giving operational users uncontrolled access to the financial asset register.
4. Make outstanding assets and exceptions visible
An audit-ready process must show more than what has been completed.
Missing, moved, damaged, duplicated, unlabelled and unverified assets should not be buried in comments or email.
Each exception should have a category, owner, current status, supporting information, required action, reviewer and final outcome.
Finance should be able to report unresolved asset exceptions before audit fieldwork begins.
5. Control transfers, movements and disposals
Asset movements create a common gap between the fixed asset register and operational reality.
Location, cost-centre and custodian changes, inter-site transfers, additions and disposals should follow a controlled process.
A proposed change should be routed to the appropriate reviewer, and an approved change should be aligned with the fixed asset register.
This creates a traceable connection between the physical event and the financial record.
6. Separate the request from the approval
Operational participation should not result in uncontrolled register changes.
A manager may verify an asset and request a location change, but the asset register custodian should review the supporting information and approve, reject or return the request.
This separation preserves the integrity of the fixed asset register while allowing the people closest to the assets to participate in the verification process.
7. Generate fixed asset audit evidence through the process
Audit evidence should be created as users verify assets, record exceptions, request changes and complete approvals.
A useful fixed asset audit trail shows the previous information, verification result, verifier, date, proposed change, reason, supporting evidence, reviewer, decision and final alignment with the register.
This gives Audit a clearer path from the physical asset to the governed record and reduces retrospective evidence gathering.
How should fixed asset audit readiness be monitored?
Traditional fixed asset verification processes often provide visibility only after all files have been returned and consolidated.
That is too late to manage audit readiness effectively.
Finance and asset custodians should be able to monitor completion by site, manager and asset class, as well as:
- Unverified assets.
- Unresolved exceptions.
- Pending transfers.
- Disposals awaiting approval.
- Overdue verification.
- Other outstanding actions.
This turns fixed asset audit readiness into a monitored condition rather than a last-minute project.
Why does current fixed asset verification evidence matter?
Audit evidence must be traceable, but it should also reflect the asset's current operational position.
During a long verification cycle, assets move, custodians change, new assets enter service and disposals occur. Some evidence may therefore be much older than other evidence by final reporting.
The organisation should be able to identify when each asset was last verified and assess the age of the evidence.
Scheduled or risk-based verification can reduce dependence on one lengthy annual exercise where the governance model supports it.
How can mobile asset verification help?
Mobile QR verification can connect the physical asset directly to its digital record.
An authorised user can scan an asset with a standard mobile device and capture the verification result at the asset's location.
This can reduce printed-list searches, handwritten notes, later data entry, spreadsheet consolidation and delays between verification and reporting.
However, scanning alone does not create audit readiness.
Mobile asset verification should form part of a controlled process that includes role-based access, assigned responsibility, exception management, approvals, audit history, reporting and alignment with the fixed asset register.
What evidence is required for a fixed asset audit?
The exact requirements will depend on the organisation, audit scope and applicable accounting and control framework. However, an audit-ready fixed asset process should generally be able to provide evidence covering:
- The assets included in the verification population.
- The date and result of physical verification.
- The person responsible for each verification.
- Asset location, custodian or cost-centre information.
- Exceptions and unresolved differences.
- Transfers and movement history.
- Additions and disposals.
- Supporting documentation.
- Review and approval history.
- Changes made to the fixed asset register.
- Reconciliation between operational verification and the financial record.
The important point is not simply having these documents. The evidence should be traceable and connected to the asset and the control process that produced it.
Can your ERP remain the system of record?
Improving fixed asset audit readiness does not require replacing the ERP or fixed asset register.
The existing register can remain the authoritative financial record for accounting, asset values, depreciation and statutory reporting.
An operational control layer can work alongside it by supporting:
- Distributed asset verification.
- Responsibility by location or cost centre.
- Current asset status.
- Exception visibility.
- Transfer and disposal requests.
- Review and approval.
- Audit history.
- Reconciliation with the fixed asset register.
This can strengthen the operational controls around the register without requiring the organisation to replace its core financial system.
A practical fixed asset audit-readiness review
Before the next audit or verification cycle, ask whether the organisation can answer these questions without manually reconstructing evidence:
- Can we identify when every in-scope asset was last verified and by whom?
- Can we report assets that remain outstanding or could not be verified?
- Can we trace movements, transfers, additions and disposals?
- Can we distinguish the person requesting a change from the approver?
- Can we retrieve the approval history and demonstrate register alignment?
- Can managers see the assets assigned to their areas?
- Can we report unresolved exceptions before audit fieldwork?
- Can verified information support audit and CAPEX decisions?
If several answers depend on finding a spreadsheet, email or paper sign-off, the organisation may have an evidence-collection process rather than an audit-ready asset-control process.
Audit readiness is an outcome of good control
Fixed asset audit readiness does not result from preparing more files shortly before the audit.
It results from a controlled operational process that defines the asset population, assigns responsibility, records physical verification, makes exceptions visible, governs changes, retains approval evidence and reports outstanding work continuously.
When these activities are connected, Finance spends less time finding evidence and more time governing the process. Managers gain clearer ownership, the asset register custodian receives structured change requests, and Audit gains a more traceable history.
The objective is not simply to prepare for the next audit. The objective is to maintain a process that remains ready for scrutiny.
How audit-ready is your fixed asset process?
Download the Fixed Asset Verification and Audit Readiness Checklist to assess verification dates, accountability, exceptions, controlled changes, approval history, manager ownership and the connection to CAPEX decisions.
Book an IDU Fixed Asset Audit Evidence Review to map how verification, exception and approval evidence is created, retained and reported.