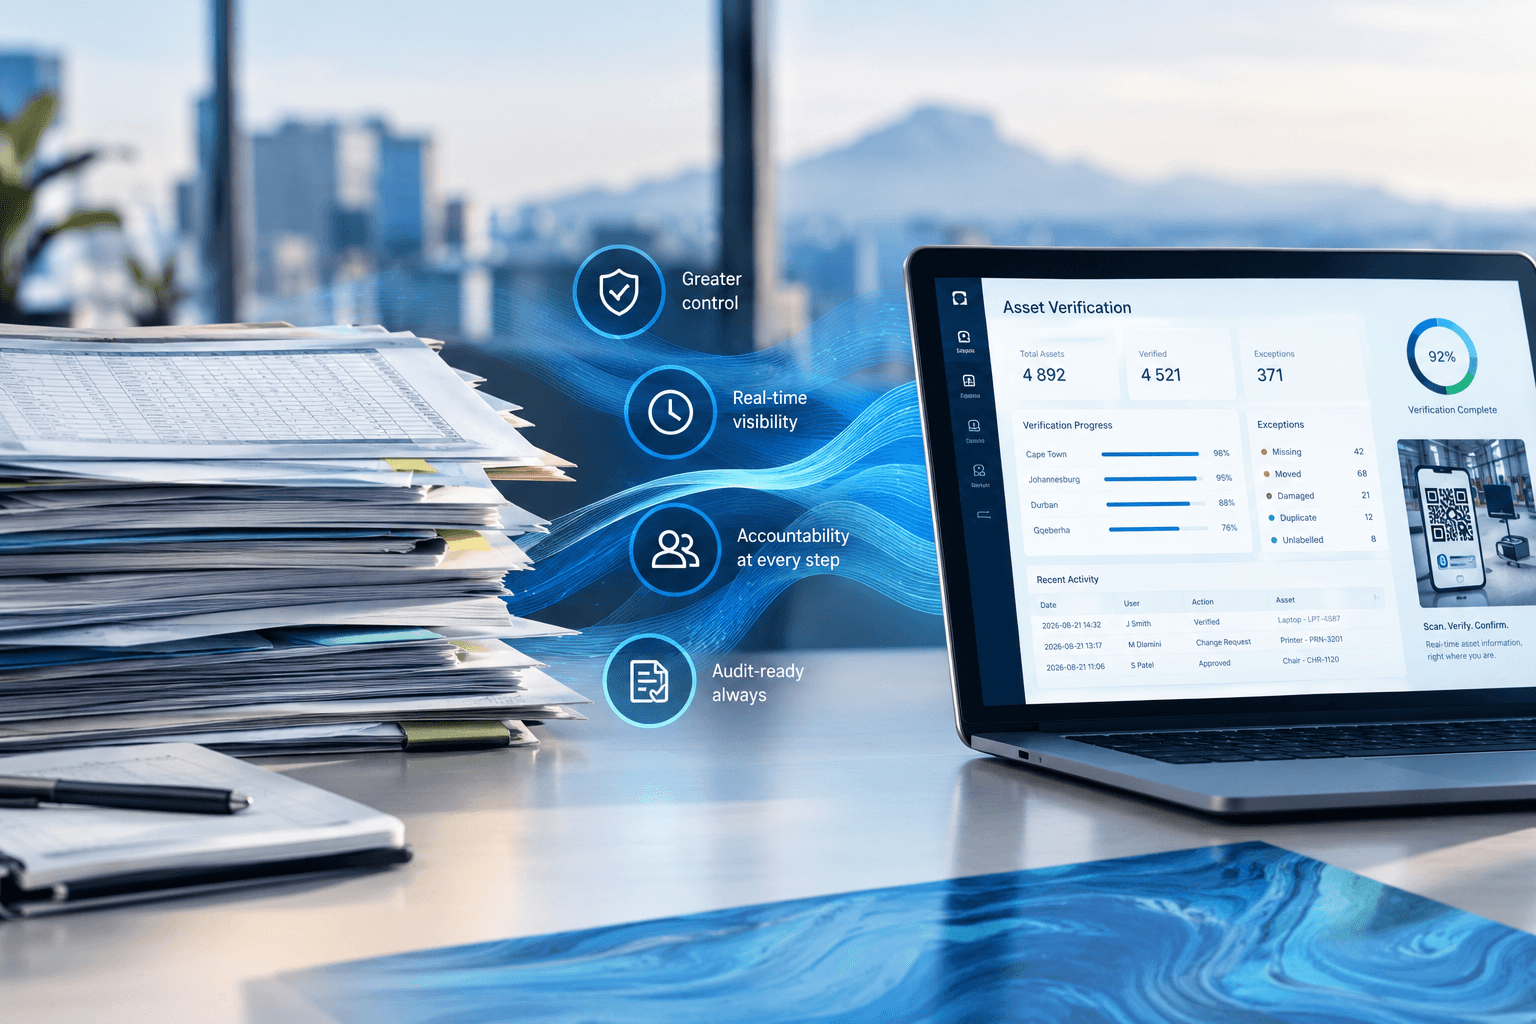
Fixed asset verification is often managed through spreadsheets, particularly when Finance needs to coordinate asset checks across multiple locations, departments or cost centres. But as the number of assets and people involved grows, spreadsheet-based verification can become difficult to control.
The problem is not necessarily Excel itself. It is the manual process around it: distributing files, tracking completion, managing exceptions, approving changes and preparing audit evidence. Here are seven signs that your fixed asset verification process has outgrown spreadsheets.
What is fixed asset verification?
Fixed asset verification is the process of physically confirming that assets recorded in an organisation's fixed asset register actually exist and that important information such as location, custodian and status is accurate.
Spreadsheets often play an important role in fixed asset verification. They are familiar, flexible and easy to distribute. Finance can extract the asset register, divide it by location or cost centre, and send each manager a list to complete.
For a limited asset population and a small number of users, this may be manageable. The difficulty begins as the organisation grows. More assets, locations, managers and approval requirements place pressure on a process designed around files rather than workflow.
The spreadsheet itself is not necessarily the problem. The problem is the manual activity around it, including distribution, version control, follow-up, consolidation, exception handling, approval and audit-evidence preparation.
At that point, the organisation is no longer maintaining a list. It is trying to manage a multi-user operational control process through separate files.
1. Finance spends more time managing files than managing the control
A spreadsheet cycle often begins with Finance extracting the register and preparing separate files for departments or locations. Finance must assign the lists, distribute them, explain how they should be completed, follow up on responses, check returned files, investigate conflicts and reconcile approved changes with the register.
The warning sign: Finance becomes the distributor, coordinator, consolidator and follow-up team for the entire process.
A stronger process: Finance defines the structures, responsibilities and controls, while authorised operational users verify assets within their assigned scope.
2. You are never completely sure which spreadsheet is current
Spreadsheet processes create copies. An original asset list may be saved locally, forwarded, renamed, updated and returned. Finance can receive several files with similar names but different information. Even with a naming convention, it may be unclear which file is final, whether the latest location change was included or whether changes were made after sign-off.
The warning sign: The file name, folder location or email date is being used as a substitute for formal status and version control.
A stronger process: One current view shows the asset, its verification status, its exceptions and its approval history.
3. You cannot see progress until files are returned
Finance may know that a file was sent, but not what is happening inside the exercise. Until the completed sheet returns, it can be difficult to identify which locations have started, which assets remain outstanding, how many exceptions have been found or whether a site needs support. Management visibility arrives after the operational activity rather than during it.
The warning sign: “Verification complete” is the first reliable status Finance receives.
A stronger process: Finance and asset custodians monitor progress while verification is taking place and follow up only where attention is required.
4. Exceptions are hidden inside cells, comments and emails
Verification rarely produces a simple yes or no result. An asset may be missing, moved, damaged, duplicated, unlabelled, no longer in use or assigned to the wrong custodian. In a spreadsheet, the finding may appear in a notes column or separate email. Finance must interpret it, determine the required action, find a reviewer and track the matter to resolution.
The warning sign: An exception exists as free text, but not as a controlled item with an owner, status and next action.
A stronger process: Each exception is visible, assigned and tracked separately from the general verification list.
5. Transfers and disposals sit outside the verification process
Verification often reveals changes that should affect the asset register. An asset may have moved to another cost centre, require reassignment or be ready for disposal. If the spreadsheet cannot manage the next stage, the process moves into email. Finance must then connect the request, evidence and approval back to the correct spreadsheet row and asset record.
The warning sign: The spreadsheet identifies a change, but a separate manual process must govern what happens next.
A stronger process: The physical finding is linked to the proposed change, supporting information, reviewer and final decision.
6. Audit evidence must be reconstructed after the event
A completed spreadsheet may show the final answer, but Audit may also require the verifier, date, confirmed information, exception, supporting evidence, change request, reviewer, approval and resulting register update. When this history is spread across files, email threads, photographs and sign-off sheets, Finance must rebuild it.
The warning sign: Audit preparation begins with a search for documents rather than a report from the process.
A stronger process: Evidence is generated while work is completed, and outstanding verification and exceptions are visible before fieldwork.
7. The information is ageing before consolidation is complete
Physical assets continue to move while verification is under way. An asset checked early in the cycle may change location before another site finishes. A custodian may change, an asset may be transferred, or a disposal may occur while Finance is waiting for outstanding files. The annual exercise may be complete, but the consolidated result may not represent one current operational position.
The warning sign: Completion does not give management confidence that the information is still current.
A stronger process: Verification is captured directly, becomes visible sooner and can be completed in parallel across locations.
The issue is not Excel. It is the operating model
Excel remains valuable for analysis, working papers and reporting. The issue arises when a file is expected to provide capabilities that belong to a controlled multi-user process.
· A status column is not the same as a monitored verification workflow.
· A manager name is not the same as access based on responsibility.
· A note is not the same as an assigned and tracked exception.
· A proposed location is not the same as an approved transfer.
· A signed spreadsheet is not the same as an audit trail generated through the process.
The point is not to eliminate every spreadsheet. It is to ensure that the core control does not depend on disconnected files, informal follow-up and retrospective reconstruction.
What does a better fixed asset verification process look like?
The future process should not simply turn the existing spreadsheet into an online form. It should address the operational requirements the current process is struggling to manage.
One current view. The existing ERP or asset register remains the system of record, while an operational layer supports verification, workflow and reporting.
Responsibility at source. Authorised managers see the assets, locations or cost centres for which they are responsible. Finance retains control over structures, access, review and approval.
Verification where the asset is located. Mobile QR scanning links the physical asset to its digital record and supports direct field verification.
Visible exceptions. Missing, moved, damaged, duplicated and unverified assets remain identifiable and actionable.
Governed changes. Operational users propose changes, while register updates remain subject to review and approval.
Evidence created automatically. The history shows who acted, what changed, when it happened and how it was approved.
A connection to Finance. Verified information supports audit readiness, CAPEX planning, budgets, forecasts and management reporting.
From spreadsheet administration to operational control
A spreadsheet-based process rarely fails in one dramatic moment. It becomes progressively harder to control. More files are created, more people require follow-up, more exceptions sit in different places, and more evidence must be gathered after the event.
These are not only administrative inconveniences. They indicate that the organisation is managing operational asset control through a tool designed primarily to organise information.
The next step is not necessarily to replace the asset register. It is to establish a connected process around it, giving Finance the governance it needs, managers visibility of the assets they control, and Audit a traceable path from physical verification to approved change and financial reporting.
Has your verification process outgrown spreadsheets?
Download the Fixed Asset Verification and Audit Readiness Checklist to assess verification dates, outstanding assets, movements, approvals, manager visibility and the connection to audit and CAPEX decisions.
Book an IDU Asset Verification Process Review to map your current files, hand-offs, approvals and reconciliation steps against a controlled future process.
Frequently Asked Questions
How do you verify fixed assets?
Fixed asset verification involves physically checking that assets recorded in an organisation's fixed asset register exist and that key information, such as location, custodian, condition and status, is accurate. The process should also capture discrepancies, transfers, disposals and other changes so that the asset register can be kept up to date.
Can fixed asset verification be managed using Excel?
Yes, spreadsheets can work for smaller organisations or straightforward verification exercises. However, as the number of assets, locations and people involved increases, spreadsheet-based processes can become difficult to control. Multiple versions, manual consolidation, email follow-ups and limited visibility of progress can increase the risk of errors and make audit evidence harder to maintain.
When should a business move away from spreadsheet-based asset verification?
There is no single point at which an organisation must move away from spreadsheets. However, if Finance is spending significant time managing files and follow-ups, teams are working from different versions, verification progress is difficult to track, or exceptions and asset movements are being managed outside the main process, it may be time to consider a more controlled digital solution.
What is fixed asset verification software?
Fixed asset verification software helps organisations manage the process of checking physical assets against the information recorded in their asset register. Depending on the solution, it can provide features such as mobile verification, QR or barcode scanning, exception management, workflow, approvals, reporting and an audit trail.
What is the difference between fixed asset verification and fixed asset management?
Fixed asset verification focuses on confirming that assets exist and that the information recorded about them is accurate. Fixed asset management is broader and can include the full lifecycle of an asset, from acquisition and capital expenditure through to transfers, verification, depreciation, reporting and disposal. Verification is therefore an important part of effective fixed asset management.
How does fixed asset verification improve audit readiness?
A controlled verification process creates a clearer record of what was checked, when it was checked, who performed the verification and what exceptions were identified and resolved. This means Finance can produce evidence from the verification process itself rather than having to reconstruct it from spreadsheets, emails and other files when an audit takes place.
Can fixed asset verification software work with an existing ERP?
Yes. Fixed asset verification does not necessarily require an organisation to replace its existing ERP or financial system. A suitable solution can work alongside existing systems, allowing organisations to improve the verification process while maintaining their established financial and asset records.